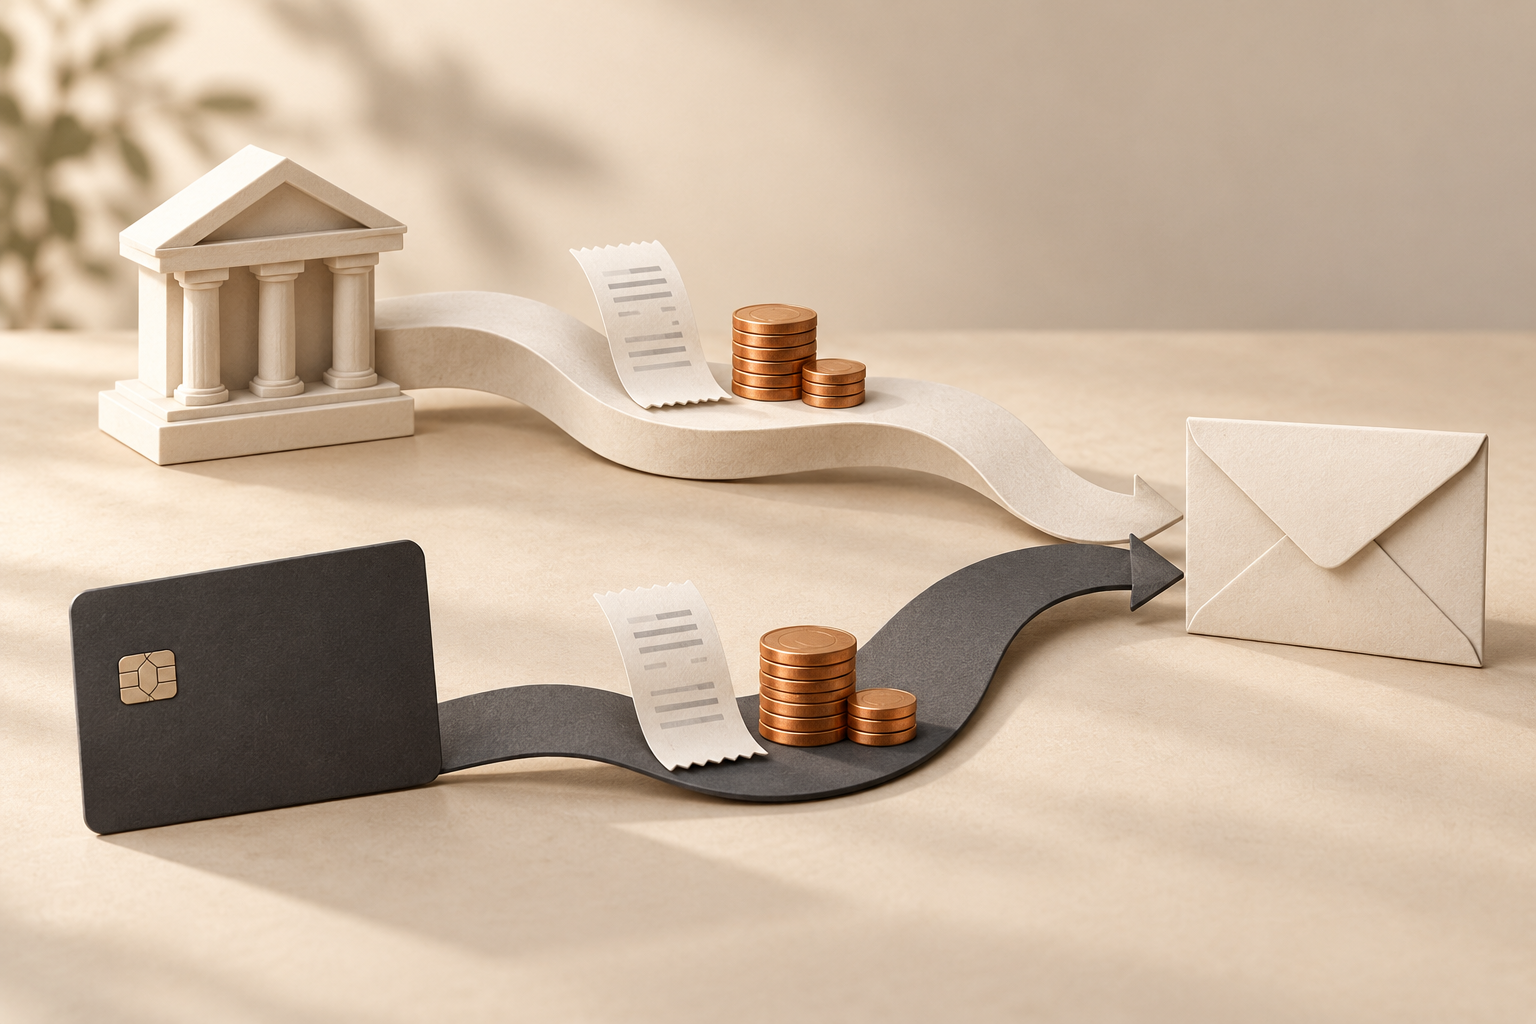
The short version: A transfer provider’s fee may not include what your card issuer charges for funding it. Compare the total account debit for the same transfer outcome, not just the fee next to the send button.
Two businesses can charge for one transfer
Wise explains that card issuers can classify transfer funding as a cash advance or withdrawal and apply their own charges. It also describes extra conversion when the card’s currency differs from the funding currency, and possible fee differences between card types. These are possible costs under Wise’s described process; they do not establish the price or treatment of your particular card.
The provider controls its quote. The issuer controls its own fee schedule and classification. A low provider fee is therefore insufficient evidence of a low total funding cost.
$3 versus $8 is only the first comparison
Hypothetical worked example—not a live quote. Assume the same $500 principal, recipient amount, exchange rate and delivery terms for both routes. Bank funding carries an invented $3 provider fee and no other fee in the example. Card funding carries an $8 provider fee plus an assumed issuer charge equal to the greater of $10 or 3% of the $500 principal. Interest is excluded.
| Component | Bank funding | Card funding |
|---|---|---|
| Principal | $500 | $500 |
| Provider fee | $3 | $8 |
| Assumed issuer charge | $0 | max($10, 3% × $500) = $15 |
| Total before interest | $503 | $523 |
The provider-fee difference is $5. The total difference is $20 because the card route also adds the assumed $15 issuer charge. Looking only at the transfer website would miss three quarters of that difference in this constructed example.
Why minimum fees matter at smaller amounts
For a $100 principal with the same assumed fee schedule, the issuer charge is max($10, $3) = $10. Total card funding is $118 versus $103 by bank, a $15 difference. The issuer charge alone is 10% of principal, even though the percentage shown in the invented schedule is 3%.
The switch between the minimum and percentage portions occurs at $10 ÷ 0.03 = $333.333… . Below that mathematical threshold the $10 minimum controls; above it the 3% calculation controls, subject to actual currency rounding. This is a calculation about the example, not a real card’s breakpoint.
Ask for the missing parts
Confirm whether the issuer treats the payment as a purchase or cash advance, what amount its percentage applies to, whether a minimum applies, and whether interest is charged. If the percentage applies to principal plus the provider fee, the $500 example’s issuer charge becomes 3% × $508 = $15.24, producing a $523.24 total before interest.
Keep funding currency, card currency and recipient currency distinct. Do not assume rewards offset costs or that bank funding is always free or equally fast. Obtain the relevant terms, then compare matched outcomes using our total-cost method. No card or provider recommendation follows from this hypothetical schedule.
Source and scope
Primary source: Wise Help Centre, extra card-funding charges. Accessed 22 October 2026. The numerical examples are independently constructed teaching examples, not provider prices. Product terms and rules can change; check the terms that apply to your transaction.
This article is financial education, not personal financial advice or a product recommendation. It contains no paid links. See our disclaimer.