Minimum transfer fees can make four small payments more expensive than one larger payment, even when the total amount sent is identical. The difference depends on how the fee is calculated: a minimum charge, a fixed charge added to a percentage, or a percentage alone.
Here is a way to compare those structures without confusing the amount transferred with the total taken from your account.
What a minimum transfer fee actually means
Suppose a fictional service charges 1% of the transfer principal, with a $3 minimum per transfer. Its fee is whichever is higher: 1% of the amount or $3. It does not charge both amounts together.
That distinction has a real-world basis, but the numbers here are invented. Wise’s fee explanation describes percentage-based pricing that varies by currency and a minimum fee for small transfers. It does not establish a universal $3 minimum or a 1% rate. The applicable quote must be checked for the particular route and payment method.
One $400 transfer versus four $100 transfers
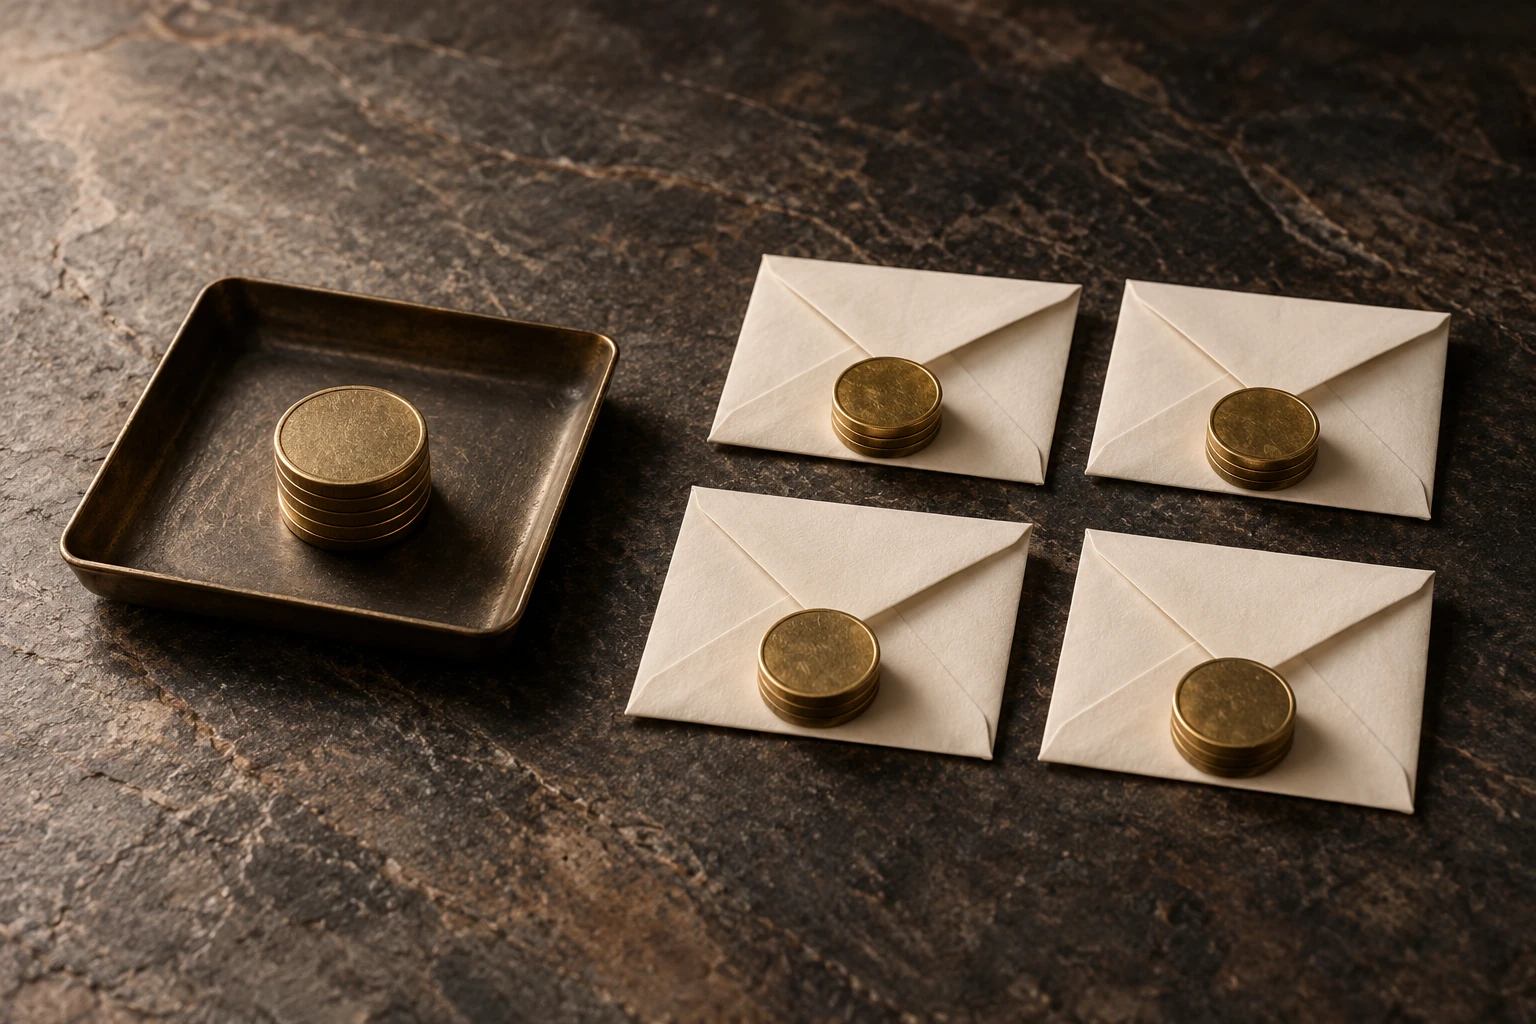
Hypothetical example: All dollar amounts are US dollars. The same $400 total principal is converted at the same exchange rate, fees are paid on top, and there are no taxes, funding charges or receiving-bank deductions. Each transfer uses the fictional 1% fee with a $3 minimum.
- One $400 transfer: 1% is $4, which exceeds the $3 minimum. Fee: $4. Total account debit: $404.
- Four $100 transfers: 1% of each transfer is $1, so each incurs the $3 minimum. Combined fee: 4 × $3 = $12. Combined account debit: $412.
The recipient gets the same converted principal under these assumptions. The four-transfer route costs the sender $8 more. Fees equal 1% of the principal in the first case and 3% in the second.
The denominator matters: those percentages use $400 of principal, not the $404 or $412 account debit. If fees are taken out of a fixed budget instead, the recipient amounts change. Finance404’s guide to fees added or deducted explains that separate comparison.
Where the minimum stops changing the answer
In this example, the percentage fee reaches the minimum at a $300 principal: $3 ÷ 0.01 = $300. Below $300, the minimum applies. At $300, the two calculations are equal. Above it, the percentage determines the fee.
Consequently, one $1,200 transfer costs $12, while four $300 transfers also cost $12 in total. Splitting no longer increases the fee in this simplified model because none of the smaller transfers is below the threshold.
For any proposed schedule, calculate each payment separately and add the results. An average transfer amount can hide one payment below the minimum, particularly when the payments are unequal.
A fixed fee plus a percentage works differently
Now consider a second, separate fictional tariff: $2 per transfer plus 1% of principal. There is no minimum-fee rule in this model.
- One $400 transfer costs $2 + $4 = $6; total account debit is $406.
- Four $100 transfers cost 4 × ($2 + $1) = $12; combined account debit is $412.
The percentage portion totals $4 in either case. The extra $6 comes entirely from paying the $2 fixed charge three additional times.
For n transfers with total principal P, a constant fixed fee f and a constant percentage rate r, the combined fee is n × f + r × P. Compared with one transfer, the extra fixed cost is (n − 1) × f. This relationship assumes no minimums, pricing bands, discounts or rounding differences.
With a pure 1% fee and none of those complications, splitting $400 into four $100 transfers would leave the combined fee unchanged at $4. More payments do not automatically mean a higher fee.
Do not turn fee arithmetic into a timing rule
The examples hold the exchange rate constant to isolate the fee structure. Payments made on different days may receive different rates. Nor does waiting for a larger transfer necessarily fit the recipient’s needs: rent, bills and other essential payments still have deadlines.
The World Bank’s Remittance Prices Worldwide methodology treats transfer fees, exchange-rate margins and service speed as distinct comparison factors. It also warns that its observed prices are snapshots rather than substitutes for a provider’s actual quote. A lower combined transfer fee is therefore only one part of the comparison.
Funding costs or deductions at the destination can change the result too. See how the funding method adds costs and why the recipient can receive less than expected.
A five-point quote check
- Match the outcome. Compare the same total principal and recipient currency, or the same required net receipt. State which one you are holding constant.
- Identify the rule. Is the displayed charge a minimum, a fixed fee plus a percentage, or a percentage with amount-based bands?
- Add every payment. Include each applicable minimum or fixed charge. Use the actual individual amounts, not just their average.
- Include the rest of the journey. Record the exchange rate, total account debit, recipient amount, other known charges and delivery estimate.
- Keep the timing and conditions. Save the quote time and check restrictions or discounts. Never split payments to evade verification, reporting requirements or provider limits.
The useful question is not simply whether fewer transfers are cheaper. It is whether the complete set of payments, on the dates the money is needed, produces the required recipient outcome at an acceptable total cost.
Sources and limitations
Sources checked on 24 October 2026: Wise, Fees for sending money; World Bank, Remittance Prices Worldwide methodology. Neither page displayed a clear publication or revision date in the retrieved text. The access date is not a claim that either policy began on that date.
All tariffs, dollar examples and calculations in this article are hypothetical Finance404 illustrations, not live provider quotes or a recommendation to delay or combine particular payments. Real pricing can vary by corridor, amount, payment method and time. This article is general financial education, not personal financial advice.