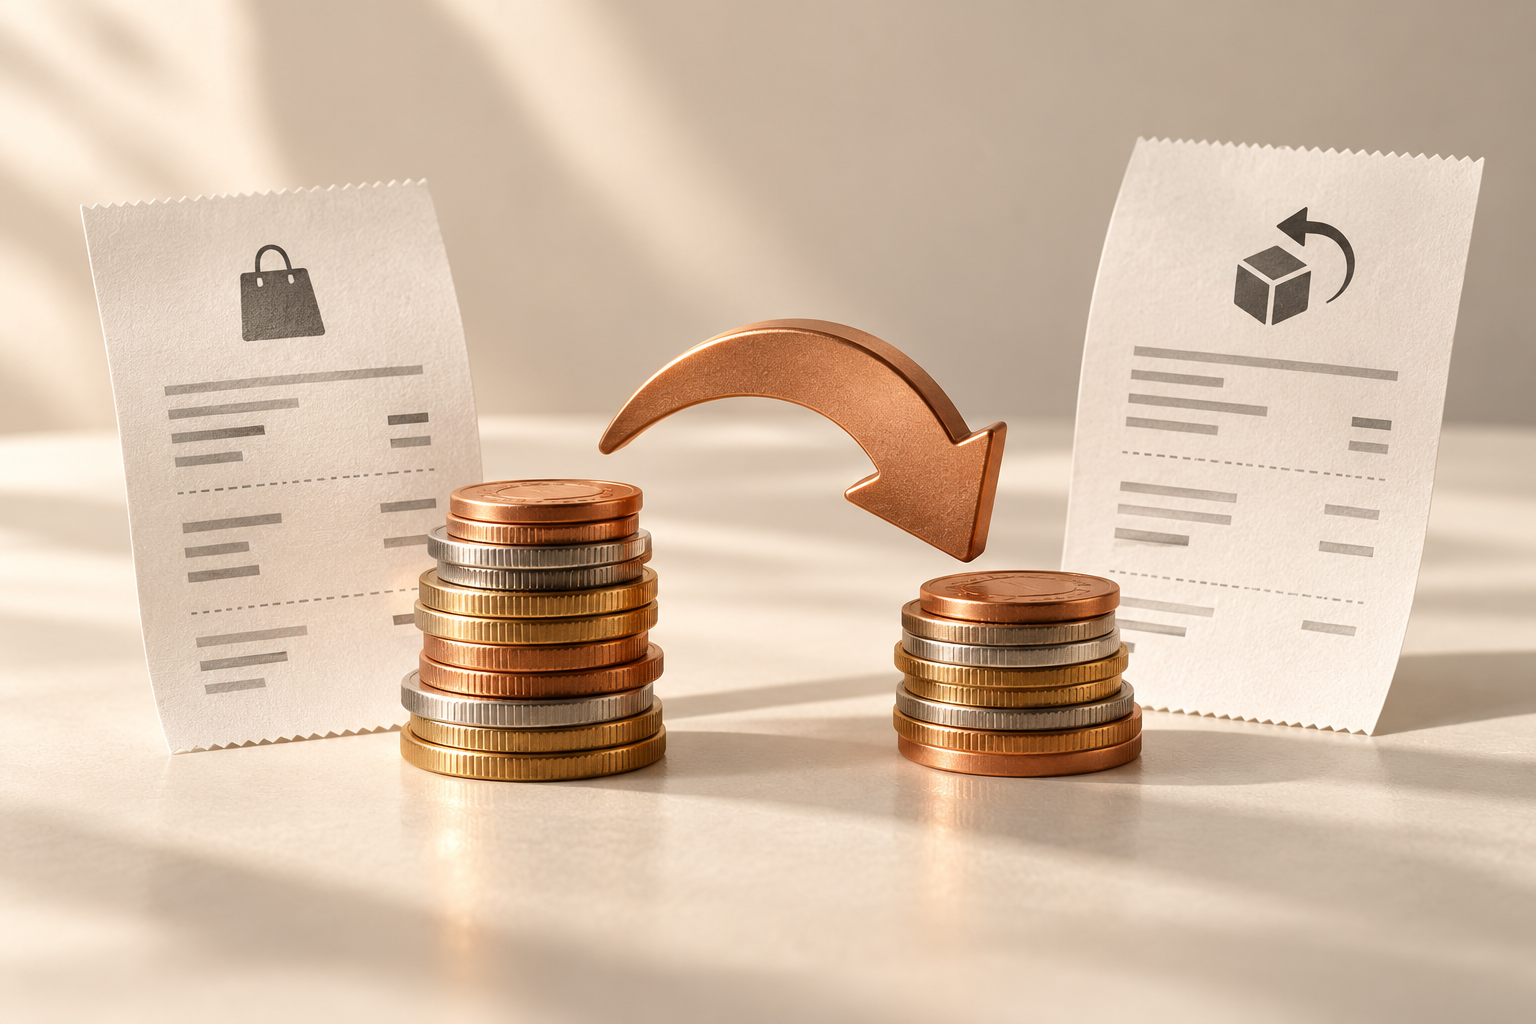
The short version: Refunding every euro of a purchase does not necessarily return every dollar originally debited. The refund can use a different conversion rate, and the original conversion charge may not be returned.
Two conversions, two dates
One concrete example is the linked Amex Bank of Canada cardmember agreement, in its foreign-currency section on printed pages 11–12. It says charges and refunds are converted when processed, refund rates may differ, original conversion commissions are not returned, and no additional conversion commission is charged on the refund. Those are terms of that agreement, not a rule for every issuer or card.
The distinction is between the merchant’s refund currency and the card account’s currency. A merchant can reverse the full purchase price while the account records a different converted amount. To understand the difference, keep the original purchase amount, both conversion rates and the treatment of fees separate.
A full €100 refund, a $4.20 difference
Hypothetical worked example—not a live quote or an Amex product calculation. Assume a generic dollar-denominated account, a €100 purchase converted at $1.10 per euro, and an invented 2% purchase conversion charge. The full €100 refund is later converted at $1.08 per euro. Assume the original fee is retained and no new refund fee is charged.
| Item | Calculation | Account amount |
|---|---|---|
| Converted purchase | €100 × $1.10/€ | $110.00 |
| Purchase conversion charge | $110 × 2% | $2.20 |
| Original debit | $110 + $2.20 | $112.20 |
| Refund credit | €100 × $1.08/€ | $108.00 |
| Unrecovered difference | $112.20 − $108 | $4.20 |
Separate the causes before calling it a fee
Of the $4.20 difference, $2 comes from conversion-rate movement: €100 × ($1.10 − $1.08). The remaining $2.20 is the original assumed charge. Describing all $4.20 as a new refund fee would be wrong under these assumptions.
The direction can reverse. If the refund rate were $1.14 per euro, the credit would be $114, which is $1.80 more than the original $112.20 debit even though the original fee was retained. That is a sensitivity example, not an exchange-rate prediction or a reason to delay a refund.
Find the break-even refund rate
With no new refund fee, the rate needed to recover the original debit is $112.20 ÷ €100 = $1.122 per euro. A different original fee, a partial refund or an extra refund charge changes that threshold. This calculation reconciles a statement; it does not decide whether a contractual or processing error occurred.
Compare the merchant’s refund confirmation with the posted account credit and read your own issuer’s conversion terms. Ask separately about the amount returned, processing dates, rates and fee treatment. Our exchange-rate denominator example explains why apparently similar percentages can answer different questions.
Source and scope
Primary source: Amex Bank of Canada cardmember agreement, printed pages 11–12. Accessed 22 October 2026. The numerical examples are independently constructed teaching examples, not provider prices. Product terms and rules can change; check the terms that apply to your transaction.
This article is financial education, not personal financial advice or a product recommendation. It contains no paid links. See our disclaimer.